Jim Cramer recently seized on another upward revision in SpaceX valuation metrics to suggest something far larger is moving beneath the surface of modern finance. Wall Street pundits love treating private space equity like a tech stock ticker, hunting for signals in secondary market transactions. But Cramer misses the structural mechanics driving this anomaly. When institutional investors push private market pricing into unprecedented territory, they are not simply betting on rocket launches or satellite bandwidth. They are pricing in the systematic dismantling of sovereign aerospace budgets and the construction of a private orbital toll road that bypasses traditional capital markets entirely.
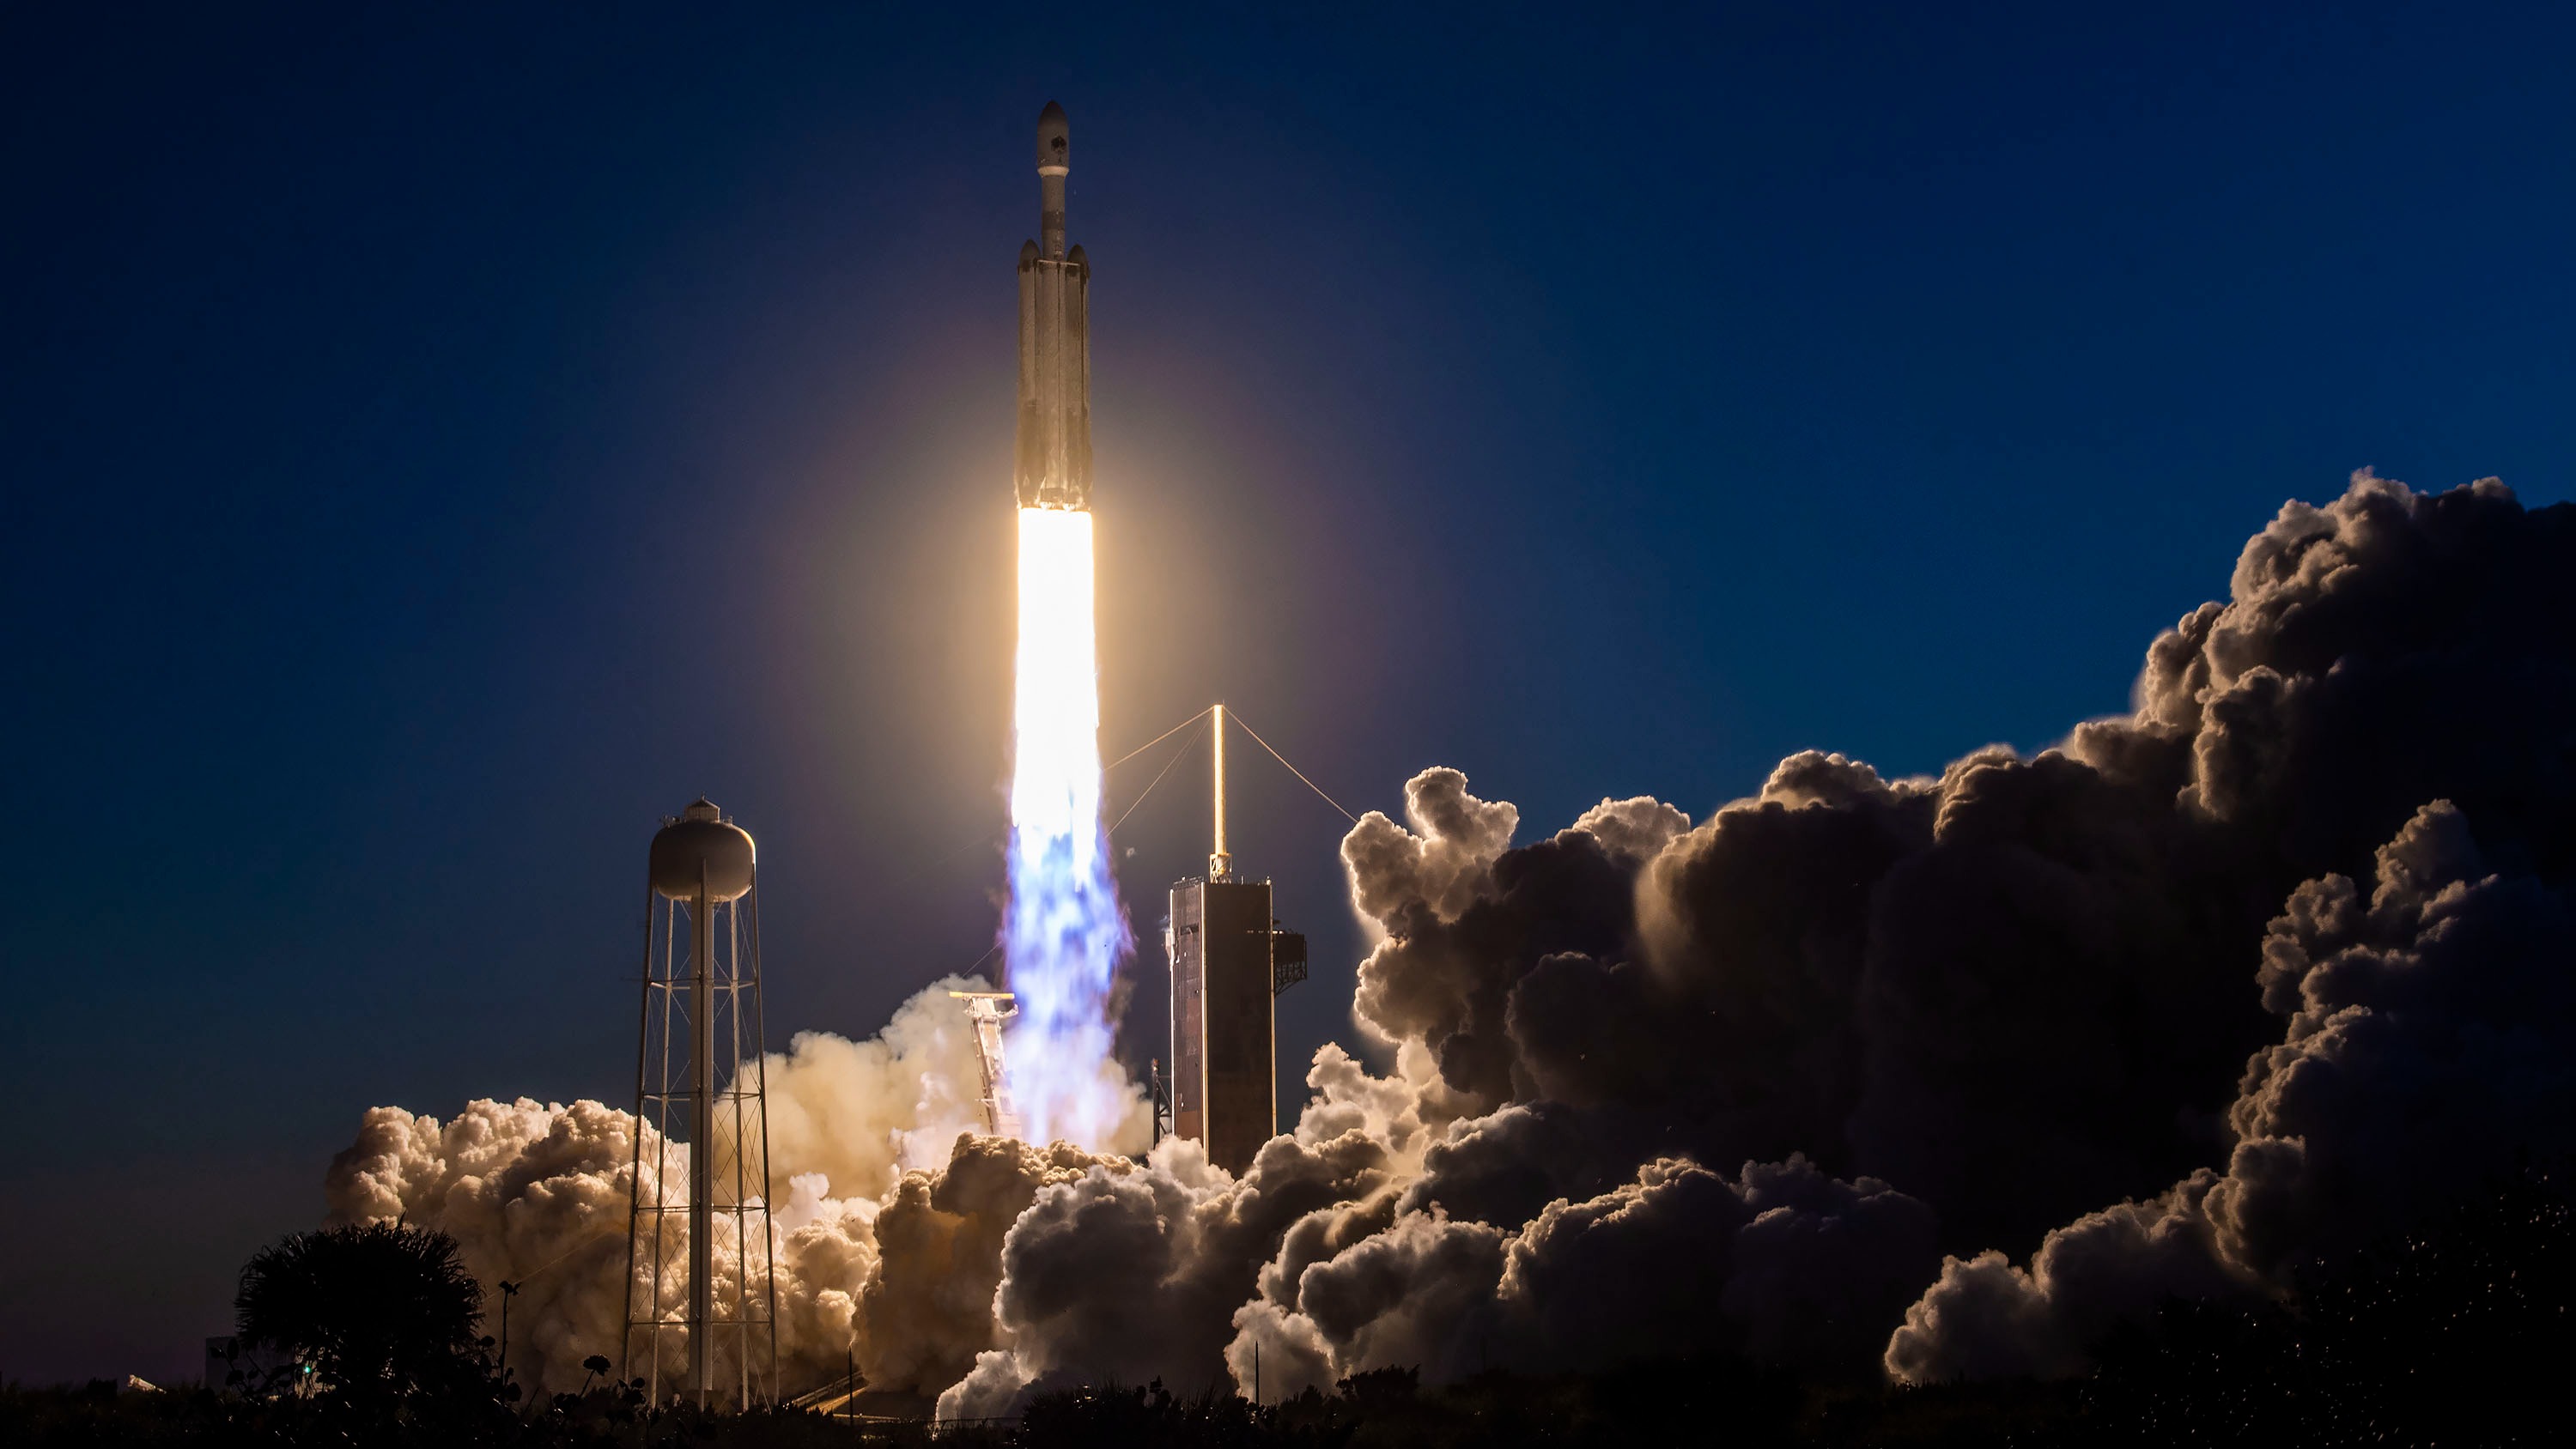
The narrative surrounding private aerospace usually focuses on hardware. Reusable boosters, titanium grid fins, and Raptor engines dominate the headlines. Yet the real financial story resides in vertical integration and liquidity velocity. Traditional defense primes operate on cost-plus contracts, bloated supply chains, and decades-long procurement cycles governed by congressional committees. SpaceX bypassed that bureaucratic architecture by keeping development in-house, retaining private ownership, and utilizing internal cash flows from Starlink to fund heavy research and development.
When a private enterprise reaches a valuation that rivals top-tier public conglomerates without needing a traditional initial public offering, the traditional rules of market analysis break down. Analysts accustomed to quarterly earnings reports, P/E ratios, and dividend yields find themselves staring at a black box. They look at a price target hike and see bullish sentiment. Veterans of defense economics see an industrial monopoly consolidating power faster than any regulatory body can map.
The Capital Trap Facing Legacy Defense
Look at the traditional defense industrial base. Lockheed Martin, Northrop Grumman, and Boeing rely heavily on government appropriations. Their profitability is tied directly to government cost-plus contracts, where efficiency is often penalized by lower future budgets. If a contractor finishes a project under budget, the following year's allocation shrinks. This perverse incentive structure rewarded stagnation for half a century.
SpaceX flipped this dynamic into a lethal competitive advantage. Fixed-price contracting forced engineering discipline. If a test rocket explodes on a pad in Texas, the cost is borne by private equity and retained revenue, not taxpayers. By absorbing that risk internally, the company developed a launch cadence that rendered legacy aerospace launch providers obsolete almost overnight.
When private market valuations climb in response to these milestones, the market is pricing in structural displacement. Competitors cannot simply copy the hardware; they have to replicate an entire corporate culture that operates with the urgency of a startup and the scale of a superpower. Wall Street analysts attempting to apply standard valuation multiples to this entity are using a measuring tape on a hurricane.
Starlink and the Global Utility Monopolization
The valuation surge is not driven by heavy-lift rocketry alone. Falcon 9 and Starship grab the media attention, but Starlink represents the recurring revenue engine that changes the financial equation entirely. Traditional telecommunications infrastructure requires massive capital expenditure to lay undersea cables or erect rural cell towers. Starlink bypasses terrestrial geography.
By placing thousands of low-Earth orbit satellites into the sky, the network transforms remote oceans, conflict zones, and rural expanses into addressable market territory. Sovereign states that once controlled their domestic communication pipelines now face an external utility provider operating outside local regulatory enforcement. When militaries, commercial airlines, and maritime shippers all rely on a single private constellation for connectivity, that entity ceases to be a mere technology company. It becomes a geopolitical infrastructure asset.
Institutional investors pouring capital into secondary rounds understand this leverage. They are buying equity in a private global utility. The price target hikes that capture headlines are merely attempts by analysts to quantify a monopoly that has no historical precedent.
The Liquidity Paradox and Private Market Maturity
Another overlooked factor in this valuation expansion is how modern capital markets handle late-stage private companies. Ten years ago, a company of this scale would have been forced into the public markets under intense regulatory scrutiny. Today, private equity, sovereign wealth funds, and specialized secondary platforms allow massive enterprises to remain private indefinitely.
This dynamic creates a profound disconnect. Retail investors and public market participants are locked out of the primary wealth-generation phase of the most consequential industrial transformation of the century. When a valuation jumps in a private round, public markets react with bewilderment because they lack access to the underlying balance sheet.
The financial machinery supporting these valuations relies on a closed loop of institutional confidence. As long as internal cash flow from commercial satellite deployment covers operational burn, the company remains insulated from public market volatility. There is no earnings miss that will trigger a sudden panic sell-off from retail shareholders.
What the Pundits Get Wrong
Cramer and other commentators often frame these financial shifts as indicators of broader market health or enthusiasm for high-risk innovation. That interpretation is too superficial. The upward pressure on private space valuations signals a growing realization that certain foundational sectors are transitioning from public oversight to private dominion.
Governments are no longer the primary architects of orbital access; they are now anchor tenants leasing services from a private provider. When the landlord holds a total monopoly on the doorway to space, the traditional rules of supply, demand, and valuation cease to function. The numbers climbing on analyst terminals are not speculative bubbles. They are the market slowly waking up to a new balance of power where private capital commands the high ground.