The demographic arithmetic of Hong Kong leaves no room for comforting illusions. By 2034, consumption expenditure among residents aged 60 and older is projected to scale a massive HK$500 billion, up from roughly HK$340 billion. Financial Secretary Paul Chan has publicly framed this structural shift as a commercial frontier, a fresh arena of untapped opportunity for local enterprise. Yet behind the optimistic rhetoric of official policy addresses lies a more complicated operational reality. Translating demographic inevitability into commercial viability requires overcoming deep structural bottlenecks that policymakers rarely address in public announcements.
For decades, the local corporate ecosystem treated aging populations as a social welfare burden rather than a core addressable market. Medical expenditure already consumes an outsized share of public resources, and the old-age dependency ratio continues to climb at an unyielding pace. When officials label this sector an economic salvation, they are banking heavily on gerontechnology, automated care coordination, and cross-boundary retirement models extending into the neighboring Greater Bay Area. But building a functional market for older consumers demands more than theoretical projections and high-level optimism. It requires solving acute supply chain failures, labor shortages in care facilities, and a profound mismatch between what seniors can afford and what technology startups actually build. For an alternative look, read: this related article.
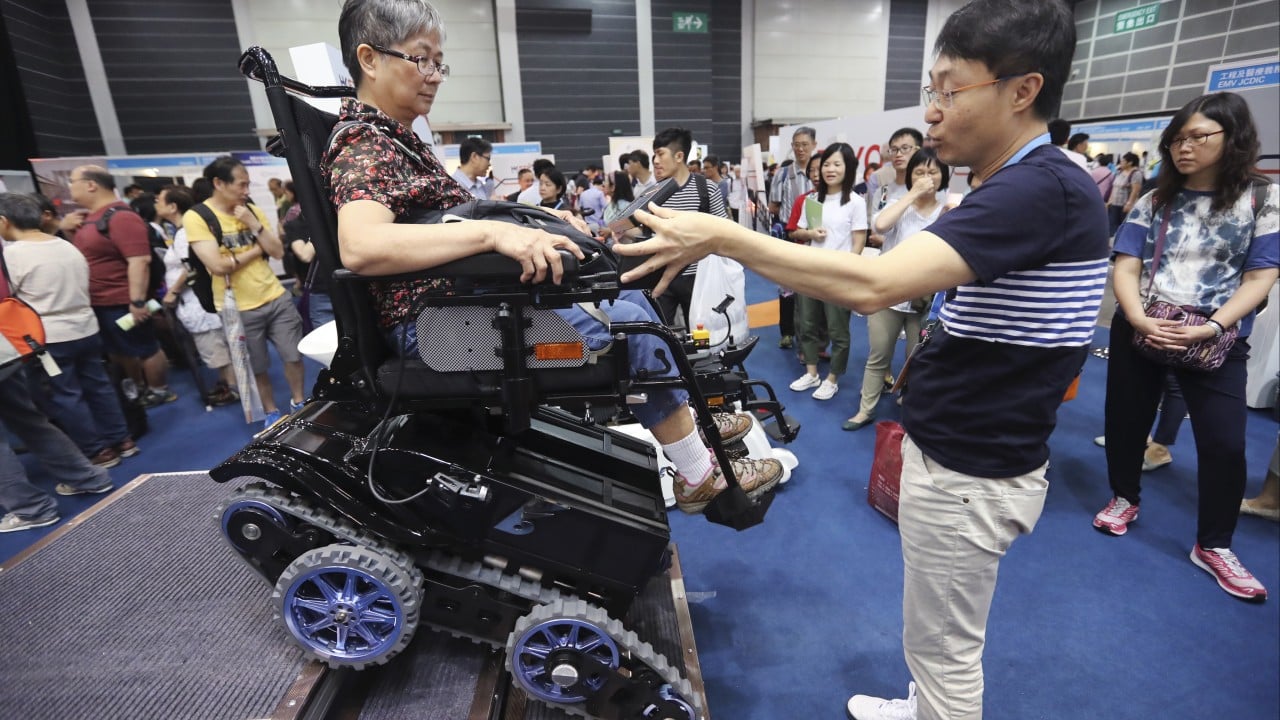
Consider the prevailing enthusiasm for high-end ambient monitoring systems and millimeter-wave radar fall-detection tools. While these innovations attract venture backing and government grants, their adoption rate among average retirees remains sluggish. Many older households operate on fixed incomes or conservative savings, making expensive smart-home installations an impossible luxury rather than an accessible utility. The commercial blind spot is glaring. Tech developers frequently design premium gadgets for affluent seniors while ignoring the vast majority of middle- and lower-income retirees who grapple with chronic mobility issues and limited digital literacy.
Furthermore, the cross-boundary solution championed by economic planners carries its own friction. Encouraging Hong Kong retirees to settle across the border in Shenzhen or Guangzhou to stretch their pensions sounds pragmatic on paper. In practice, elderly consumers face formidable anxieties regarding mainland medical insurance integration, continuity of pharmaceutical prescriptions, and separation from established local community networks. Administrative harmonization between jurisdictions moves at a glacial pace compared to the rapid graying of the population. Until cross-border healthcare portability becomes seamless and foolproof, migration southward will remain an option for only a niche demographic. Similar reporting on this matter has been provided by MarketWatch.
To capture the true value of this emerging economy, businesses must abandon generalized assumptions about older demographics. Wealth distribution among seniors is sharply polarized. A distinct tier of retirees possesses significant liquid capital and disposable income, while another expanding segment relies heavily on public subsidies and familial support. Companies failing to segment their offerings across these economic divides will watch their products stall out. The path forward demands radical product localization, transparent pricing models, and service frameworks designed for actual consumer behaviors rather than executive boardroom projections. The financial horizon is real, but navigating it demands clear eyes and disciplined execution.