Forgiving local authority housing debt does not conjure physical bricks, skilled bricklayers, or planning permissions out of thin air; it merely shifts a liability from a municipal balance sheet onto the central Treasury ledger. When backbench Labour MPs urge the Chancellor of the Exchequer to wipe out historic Housing Revenue Account (HRA) debts to accelerate social house building, they are proposing a balance-sheet restructuring disguised as a supply-side stimulus. To understand whether this policy can actually increase housing starts, one must dissect the mechanics of municipal accounting, the macroeconomic constraints of the UK gilt market, and the structural bottlenecks currently paralyzing local authority development pipelines.
The Mechanics of the Housing Revenue Account
To evaluate the proposal, we must first isolate the specific financial ringfence governing council housing in England. Local authorities operate two primary accounting structures: the General Fund, which pays for everyday services like social care and waste collection, and the Housing Revenue Account, a legally ringfenced landlord account that tracks rental income against the costs of managing, maintaining, and building council homes. You might also find this connected coverage insightful: The Quiet Rise of Sunshine Buns (And Why Four Friends in Utah Just Raised Seven Million Dollars).
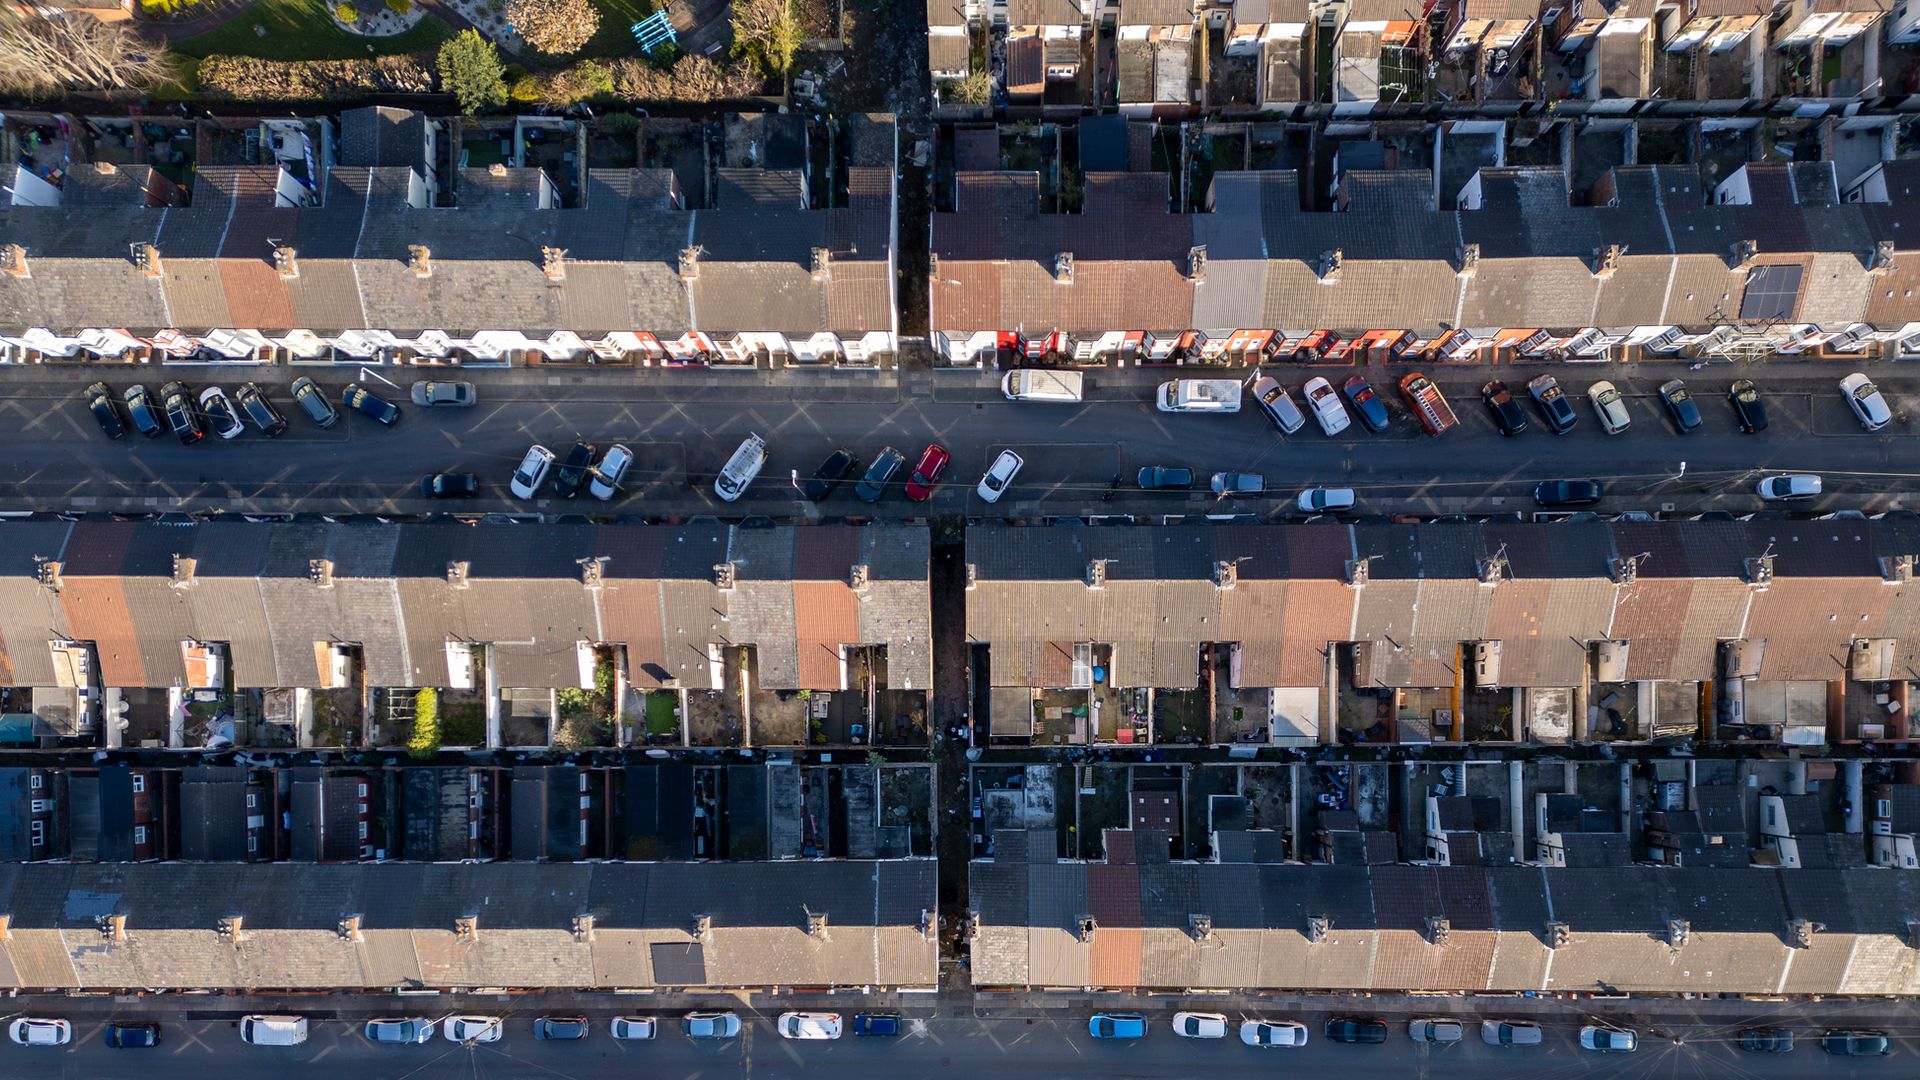
Under the 2012 self-financing settlement introduced by the coalition government, councils took on a one-off reallocation of historic housing debt—totaling roughly £29 billion across England—in exchange for retaining their local rental receipts rather than surrendering them to Whitehall. That debt is held predominantly through the Public Works Loan Board (PWLB), an operational arm of the UK Debt Management Office.
When MPs call for debt forgiveness, they are specifically targeting this PWLB principal and its associated interest payments. The operational logic is straightforward: As discussed in latest articles by Harvard Business Review, the results are widespread.
- Cash Flow Liberation: Every pound spent servicing historic debt principal and interest is a pound unavailable for capital expenditure or routine maintenance.
- Borrowing Headroom: Although the formal HRA borrowing cap was abolished in 2018, councils remain bound by the Prudential Code, which requires all borrowing to be affordable, prudent, and sustainable. High existing debt-service ratios choke off a council's ability to take on new loans for land acquisition and construction.
- Asset Maintenance Triage: Facing mandatory post-Grenfell building safety upgrades and impending decent homes energy efficiency standards, many HRAs are currently cannibalizing their new-build budgets simply to keep existing stock legally habitable.
Wiping the slate clean immediately converts a cash-flow deficit into an operating surplus on the local HRA ledger. In theory, a debt-free HRA can pledge its unencumbered future rental stream as collateral to raise fresh capital for new developments.
The Macroeconomic Illusion of Debt Cancellation
A rigorous analysis cannot stop at the town hall boundary. Because PWLB loans are assets held by the central government—backed by gilts issued by the Debt Management Office—forgiving council debt does not erase the liability from the UK public sector balance sheet. It simply transfers the servicing cost from local council tenants to national taxpayers.
This creates three immediate macroeconomic friction points for the Treasury:
- Public Sector Net Debt (PSND) Neutrality vs. Fiscal Headroom: While PSND consolidates central and local government debt—meaning an intra-governmental write-off looks neutral on certain consolidated metrics—it directly impairs the central government's current budget balance. The Treasury loses a guaranteed stream of interest income from local authorities while remaining legally obligated to pay coupon yields to international bondholders on the underlying gilts.
- The Gilt Market Signaling Risk: Following the market turmoil of autumn 2022, the UK Treasury operates under intense scrutiny from sovereign debt investors. Any policy perceived as unfunded fiscal expansion or arbitrary debt monetization risks pushing up gilt yields. If bond markets demand a higher risk premium on UK sovereign debt, the borrowing costs rise not just for Whitehall, but for every housing association, private developer, and mortgage holder in the country.
- Moral Hazard and Capital Allocation: Unconditional debt relief rewards councils that failed to manage their asset portfolios efficiently while penalizing prudent authorities that steadily paid down their 2012 settlements or structured viable cross-subsidy development models. Without strict conditionalities, central government capital is distributed based on historical liability rather than present-day delivery capacity.
The Four Non-Financial Bottlenecks
Even if the Chancellor absorbed the fiscal hit and cleared every pound of HRA debt tomorrow, housing completions would not surge proportionally. Capital availability is rarely the sole binding constraint in UK public sector house building. Injecting liquidity into a constrained production system without removing operational bottlenecks simply inflates input prices.
1. Construction Labor Scarcity and Wage Inflation
The UK construction sector faces a structural demographic deficit. An aging workforce, combined with post-Brexit labor market friction, has left acute shortages in specialized trades—bricklayers, electricians, scaffolders, and site managers. When multiple local authorities simultaneously deploy newly freed capital into the same regional labor pools, they bid up subcontractor day rates. The result is higher build costs per unit rather than higher unit volume.
2. The Planning and Statutory Consultee Quagmire
A debt-free balance sheet does not accelerate a planning application stuck in a local authority's own development management department. Councils face severe shortages of qualified town planners. Worse, major developments require sign-off from external statutory consultees—Natural England, the Environment Agency, National Highways, and local water companies. Nutrient neutrality rules, biodiversity net gain calculations, and sewage capacity objections routinely stall shovel-ready sites for years, regardless of how cheap the underlying financing is.
3. Viability Erosion and Build-Cost Hyperinflation
Between 2021 and 2024, construction material costs surged due to energy price shocks and supply chain disruptions. Simultaneously, high interest rates depressed the open-market value of private homes. Many council development arms rely on a cross-subsidy model: building mixed-tenure estates where profits from private-sale units subsidize the construction of social-rent units. As build costs rose and private sale values stagnated, the residual land value of countless schemes turned negative. Debt forgiveness lowers the cost of capital for the social element, yet it does not fix broken unit economics on the private-sale component.
4. Right to Buy Leakage
Under current statutory rules, council tenants can purchase their homes at substantial discounts after a qualifying period. Historically, the receipts retained by councils were insufficient—and too heavily restricted—to replace the sold stock on a one-for-one basis. Building new social housing without reforming or suspending Right to Buy discounts is akin to pouring water into a punctured bucket. Clearing historic debt to fund new builds only for those assets to be sold off at a discount five years later represents a permanent transfer of public wealth to private individuals at the taxpayer's expense.
Separating Maintenance Liabilities from Growth Capital
The backbench campaign conflates two distinct financial problems: the solvency of existing social housing stock and the financing of net-new housing supply.
Many urban councils—particularly in London and major metropolitan boroughs—are facing imminent HRA insolvency not because they are building too much, but because the cost of retrofitting aging tower blocks for fire safety and damp remediation has outstripped inflation-capped rental income. For these authorities, debt forgiveness is an emergency bailout to prevent Section 114 bankruptcy notices. Every penny saved on PWLB interest would be immediately absorbed by cladding remediation, roof replacements, and compliance with Awaab's Law on damp and mold. Zero additional homes would be built.
Conversely, growth-ready councils with shovel-ready land banks and established in-house development teams face a different constraint: the cost of borrowing for new capital expenditure. For these authorities, high PWLB interest rates—which are pegged to gilt yields plus a margin—make new social rent developments mathematically unviable over a 30-to-40-year appraisal window.
Treating both cohorts with the blunt instrument of blanket debt cancellation is capital inefficiency at its worst. It uses scarce fiscal headroom to plug operational maintenance holes in non-building councils while failing to guarantee that growth-capable councils actually break ground.
Alternative Capital Restructuring Mechanisms
If the strategic objective is maximizing net-new social housing completions per pound of Treasury fiscal cost, blanket debt forgiveness is inferior to targeted financial engineering. The Treasury possesses three sharper instruments that achieve supply expansion without destabilizing the gilt market.
Targeted PWLB Concessionary Rates for Net-New Supply
Instead of cancelling historic debt, the Treasury can expand the discounted HRA PWLB lending rate specifically for capital expenditure tied to net-new social housing starts. By subsidizing the interest rate on new borrowing rather than forgiving old borrowing, the government ensures that every pound of fiscal support directly triggers physical construction. If a council does not build, it receives zero subsidy.
Asset-Backed Securitization and Joint Ventures
Rather than holding debt directly on the HRA, councils can transfer land into wholly owned housing companies or institutional joint ventures with pension funds and insurers. Long-term institutional investors desperately seek inflation-linked cash flows over 40-to-50-year horizons—precisely the financial profile of social rent. Structuring off-balance-sheet leaseback arrangements allows councils to tap private institutional liquidity without breaching Prudential Code borrowing limits or requiring Treasury debt write-offs.
Grant Funding via Homes England
Direct capital grants—increasing the grant rate per unit through the Affordable Homes Programme—are fiscally transparent and superior to debt forgiveness. Grants appear cleanly as capital expenditure in departmental budgets, do not distort ongoing interest rate mechanisms, and can be strictly tied to build milestones, energy performance standards, and regional housing need. A 50% upfront capital grant reduces the debt required to build a home just as effectively as forgiving old debt, while maintaining rigorous central oversight over delivery.
The Strategic Imperative for the Treasury
The campaign by Labour MPs exposes a fundamental tension in British political economy: the desire for rapid, visible public infrastructure delivery colliding with rigid sovereign debt constraints. While the political appeal of freeing councils from historic debt is obvious, executing a blanket write-off would be a strategic blunder. It would surrender billions in future Treasury revenue, unsettle bond markets, and watch much of the liberated cash disappear into routine maintenance backlogs and construction wage inflation.
To unlock municipal house building without triggering a fiscal crisis, the Chancellor must reject unconditional debt forgiveness and execute a conditional, supply-linked capital strategy:
- Ringfence relief strictly for growth: Tie any debt restructuring or interest-rate relief exclusively to contractual, time-bound commitments for net-new social housing completions, verified through quarterly stage-gate audits.
- Reform the Right to Buy regime simultaneously: Eliminate or drastically reduce purchase discounts on all newly constructed council homes, and allow authorities to retain 100% of receipts from existing stock sales to reinvest directly into development pipelines.
- Deploy capital grants over debt write-offs: Channel fiscal support through elevated upfront Affordable Homes Programme grant rates rather than altering PWLB principal balances, preserving balance-sheet discipline while directly fixing project-level viability.
- Pair capital with planning deregulation: Grant automatic, streamlined planning permissions on brownfield land owned by local authorities that meet strict build-out timelines, ensuring that newly unlocked capital converts into physical completions rather than bureaucratic stagnation.